Guide
What is the Foreign Military Sales Trust Fund?
The is the U.S. Treasury account that receives purchasers' payments and from which disbursements are made against implemented cases. A payment that cannot be identified to a case goes to the purchaser's .
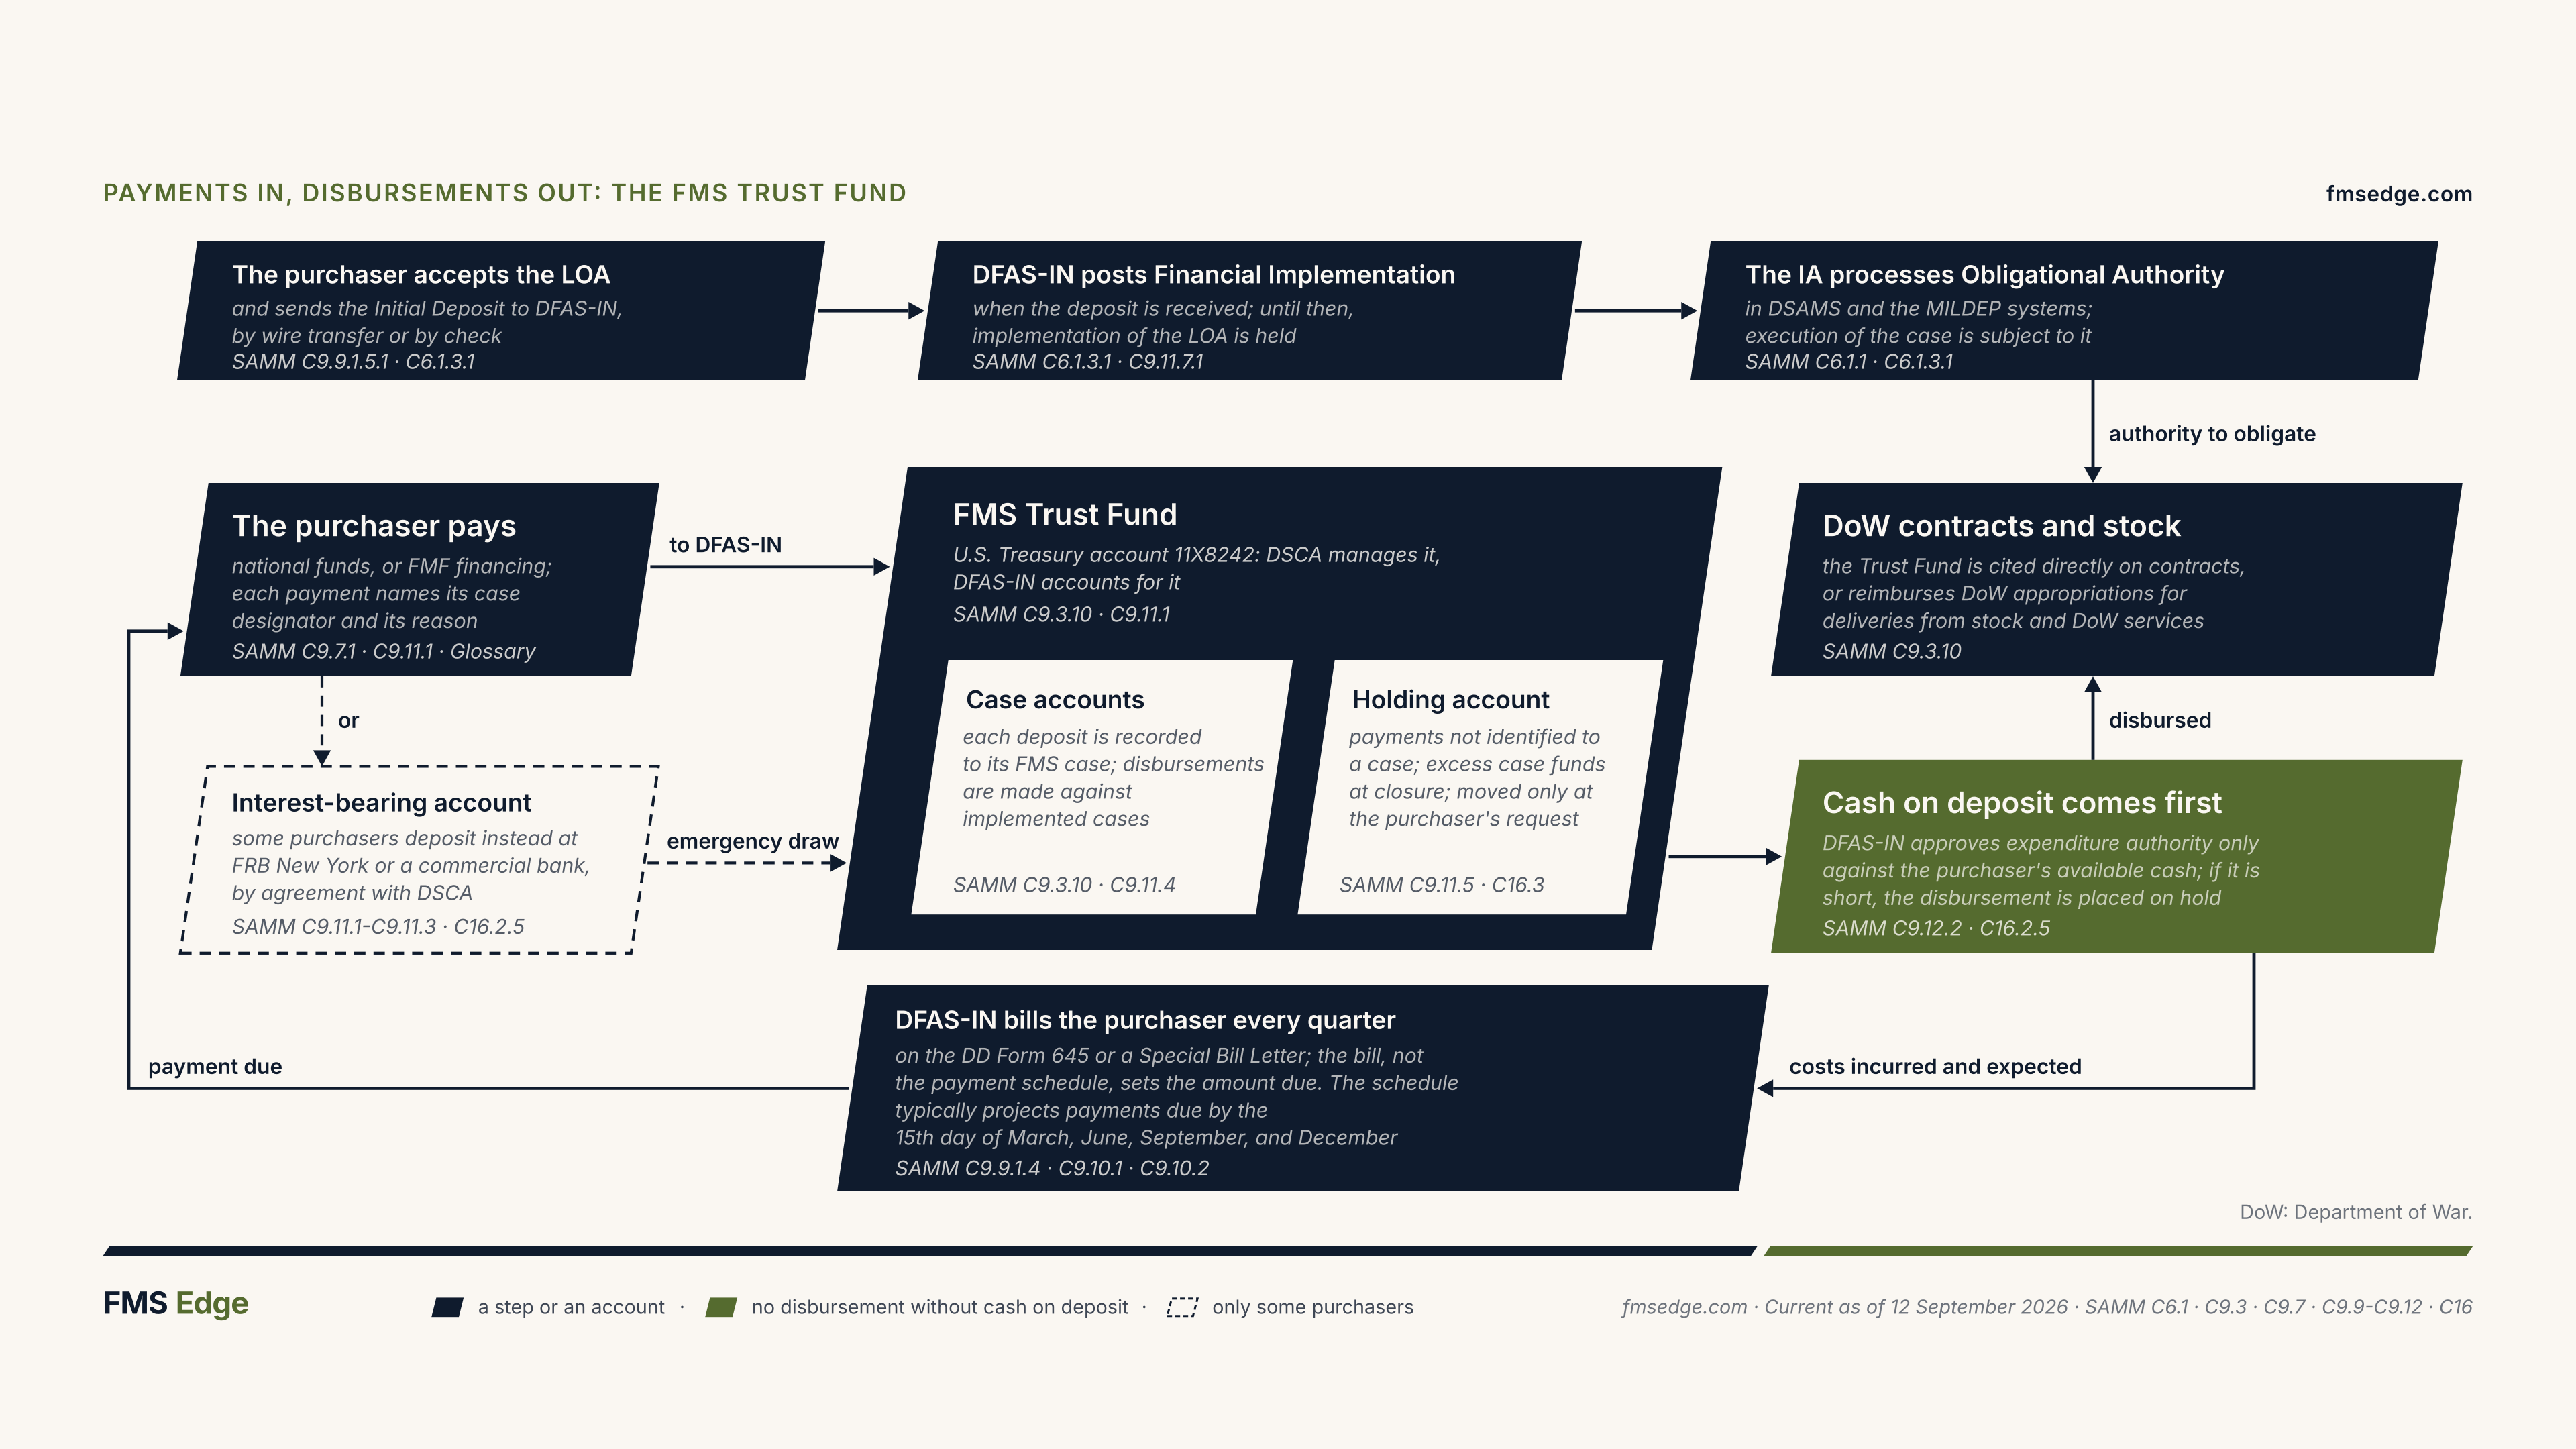
The purchaser's payments go to DFAS-IN for deposit in the FMS Trust Fund, U.S. Treasury account 11X8242, each recorded to its case. The Trust Fund pays contractors and reimburses the Department of War only against cash on deposit, and DFAS-IN bills every quarter for what the cases will need next.
What is an FMS Trust Fund?
The is a U.S. Treasury account credited with receipts, earmarked by law, and held in a fiduciary capacity by the U.S. Government (), to carry out specific () purposes and programs. The Defense Finance and Accounting Service - Indianapolis () accounts for the fund as account 11X8242, through two subsidiary accounts: 978242 for receipts and 97-11X8242 for disbursements [SAMM ]. The represents the aggregation of cash received from , and international partners []. The is responsible for management of the [SAMM ]. is responsible for accounting [SAMM ].
Purchasers' payments are received into the , and disbursements against implemented cases are made from it. The fund is either cited directly on the contracts that procure defense articles or services for a purchaser, or used to reimburse Department of War Component appropriations for deliveries from Department of War stocks and for services performed by Department of War employees. is also responsible for the solvency of each purchaser's account in the fund [SAMM ].
The glossary entry for the fund adds that it is managed as a single cash entity, whatever the source of the deposits, and that every deposit is accounted for at the level of the purchaser and of the case, by source of financing. Its examples of financing are Foreign Military Financing (), whether Credit or nonrepayable Credit, and the Merger. Among other kinds of funds it names a purchaser's , third-party funds included, and other Department of War appropriated funds. The fund's receipts must be apportioned before they are obligated and expended.
However, an official designated under 31 U.S.C. 1513 may, as 31 U.S.C. 1516 provides, exempt a from apportionment if an expenditure from it has no significant effect on the financial operations of the U.S. Government [].
The purchaser pays for deposit into the , unless it has an interest-bearing account with the Federal Reserve Bank () of New York. Each has the Information attached, which gives the fund's wire transfer and check mailing information (Figure C5.F10). Each payment must identify the case designator and the reason for the payment, and Implementing Agencies () refer collection problems and questions to [SAMM ].
A country may set up an account with the of New York for its deposits. An agreement among the purchaser's defense organization, its central bank or an acceptable equivalent, the of New York and sets the terms, conditions and mechanics under which the account operates. Purchasers should contact the of New York, or the Regional Division of 's Financial Policy and Regional Execution Directorate (/FPRE), about these accounts. Except as law or policy authorizes, of New York accounts do not hold funds; Section C9.7 covers . Signature authority for new agreements rests with the Chief Financial Officer (CFO) [SAMM ].
Each deposit into the is recorded to the case it belongs to. A payment that cannot be identified to a specific case is deposited in the purchaser's until it is identified [SAMM ].
maintains international partner holding accounts in the . The holding accounts are sub-accounts of funds that are not identified to a specific case. These funds could be a result of excess funds left when an case is closed, a quarterly payment by an international partner that does not identify to which case the payment should be applied, or as part of case cross leveling transactions [SAMM , , ]. moves to and from holding accounts, or between cases, only when the request is channeled through the purchaser’s designated representative [SAMM ]. The balances are not included in the totals of the DD Form 645, Billing Statement. Separate statement(s) (as attachment(s) to the quarterly DD Form 645), Billing Statements are provided to the country showing deposits and withdrawals to each for that country.
A purchaser may have more than one [SAMM ].
Notes or other references in documents, whether a Basic , an Amendment or a Modification, about transferring or refunding a purchaser's funds are not authorized. do not enter remarks on documents that move purchaser funds from one case to another, except on concurrent documents (Section C6.7.2.3). Such remarks can mislead, can contradict the instructions the purchaser has given , and are not effective if cross leveling is required [SAMM ].
was established in order to ensure compliance with the requirement that Department of War (DoW) funds not be used to provide interim financing of requirements. EA is an country-level authority, which allows expenditures to be incurred against obligations previously recorded against a country’s account. As a result, before expenditures can be made, the dollars must first be on deposit in the [SAMM , ] [].
References
SAMM
- SAMM C9.11.5: Excess Funds.
- SAMM C16.3.10.2
- SAMM AP7.C4.12.5
- SAMM C9.11: Foreign Military Sales Payments from Purchasers.
- SAMM AP7.C2.8.1
- SAMM C9.3.10: Foreign Military Sales Trust Fund.
- SAMM C9.11.1: Trust Fund Accounts.
- SAMM C9.11.2: Federal Reserve Bank New York Accounts.
- SAMM C9.11.4: Payment Identification.
- SAMM C9.11.6: Movement of Purchaser Funds.
Public authorities
- DoD FMR Vol 15: DoD Financial Management Regulation 7000.14-R, Volume 15 (Security Cooperation Policy)
- 31 U.S.C. §1516: 31 U.S.C. §1516, Exemptions
Facts referenced
- FMS Trust Fund, Treasury account number DFAS-IN accounts against: 11X8242 (as of 11 September 2026; SAMM C9.11.1)
Related
Foreign Military Sales (FMS)
The part of U.S. security assistance, authorized by the Arms Export Control Act (AECA), in which eligible foreign governments and international organizations buy defense articles, services and training from the U.S. Government under formal government-to-government agreements.
The articles come either from Department of War stocks or from new procurement under contracts the Department manages [22 U.S.C. 2761, 22 U.S.C. 2762]. A sale is FMS whatever the source of the purchaser's financing.
FMS Edge glossary, as of 10 October 2026
Glossary entry →Open the manual’s entry → (opens in new tab)
Trust Fund
A fund or account that law designates as a trust fund, credited with receipts that law earmarks and that the government holds in trust, in a fiduciary capacity, for specific purposes and programs under an agreement.
A trust fund account is usually a receipt account, an expenditure account or a revolving fund account.
FMS Edge glossary, as of 10 October 2026
Glossary entry →Open the manual’s entry → (opens in new tab)
Holding Account
An account established for each Foreign Military Sales country/international organization for the purpose of recording and safeguarding unidentified and certain earmarked funds for future use
SAMM Glossary, as of 12 September 2026
Glossary entry →Open the manual’s entry → (opens in new tab)
Foreign Military Sales (FMS) Trust Fund
A single account that is authorized to be credited with receipts that may be obligated and expended in accordance with the Arms Export Control Act (AECA). Foreign Military Sales (FMS) Trust Fund receipts must be apportioned prior to obligation and expenditure; however, an official, designated under 31 U.S.C. 1513 (as per 31 U.S.C. 1516), may exempt trust funds from apportionment. The FMS Trust Fund is managed as a single cash entity, regardless of the source of the deposits. All FMS Trust Fund deposits are accounted for at purchaser and FMS case level by source of financing. Examples of funds include Foreign Military Financing (FMF) (FMS Credit and FMS Credit (nonrepayable)) and the Military Assistance Program (MAP) Merger. Examples of other types of funds are a purchaser's national funds, which include third-party funds, and other DoD appropriated funds.
SAMM Glossary, as of 12 September 2026
Glossary entry →Open the manual’s entry → (opens in new tab)
Security Cooperation
Activities by which the Department of War encourages and enables international partners to cooperate with the United States toward strategic objectives, spanning every interaction with foreign defense and security establishments and every security assistance program the Department administers.
Under chapter 16 of Title 10, their purposes are to develop allied and friendly security capabilities for self-defense and multinational operations, to give U.S. forces peacetime and contingency access, and to build relationships promoting specific U.S. security interests [10 U.S.C. 301(7)].
FMS Edge glossary, as of 10 October 2026
Glossary entry →Open the manual’s entry → (opens in new tab)
DFAS-IN: Defense Finance and Accounting Service - Indianapolis
SAMM Acronyms, as of 12 September 2026
FMS: Foreign Military Sale
SAMM Acronyms, as of 12 September 2026
Defense Security Cooperation Agency (DSCA)
The Department of War agency that directs, administers and provides guidance to the Department's components and its representatives at U.S. missions for the execution of the security cooperation programs for which it is responsible [SAMM C1.3.2.2]. The agency also provides financial and technical assistance, arranges the transfer of defense materiel, training and services to international partners, and promotes military-to-military contacts.
FMS Edge glossary, as of 10 October 2026
Glossary entry →Open the manual’s entry → (opens in new tab)
DSCA: Defense Security Cooperation Agency
SAMM Acronyms, as of 12 September 2026
Glossary entry →Defense Security Cooperation Agency (DSCA) →
Military Assistance Program (MAP)
That portion of the United States Security Assistance program authorized by the Foreign Assistance Act of 1961, as amended, which once provided defense articles and services to recipients on a nonreimbursable (grant) basis. Funding for MAP was consolidated under the Foreign Military Financing program beginning in Fiscal Year 1990.
SAMM Glossary, as of 12 September 2026
Glossary entry →Open the manual’s entry → (opens in new tab)
National Funds
Source of funding that is provided directly from the purchaser.
SAMM Glossary, as of 12 September 2026
Glossary entry →Open the manual’s entry → (opens in new tab)
Letter of Offer and Acceptance (LOA)
The legal instrument that lists the defense articles and services, including training, that the U.S. Government transfers to a foreign country or international organization, with their estimated costs and the terms and conditions. The benefitting partner does not sign a Building Partner Capacity (BPC) LOA.
The Letter of Offer and Acceptance (LOA) is the instrument the U.S. Government uses to sell under the Arms Export Control Act (AECA); signed LOAs and their later Amendments and Modifications are also called Foreign Military Sales (FMS) cases [SAMM C5.6.1].
FMS Edge glossary, as of 10 October 2026
Glossary entry →Open the manual’s entry → (opens in new tab)
LOA: Letter of Offer and Acceptance
SAMM Acronyms, as of 12 September 2026
Implementing Agency (IA)
The military department or defense agency responsible for the execution of military assistance programs. With respect to FMS, the military department or defense agency assigned responsibility by the Defense Security Cooperation Agency to prepare an LOA and to implement an FMS case. The implementing agency is responsible for the overall management of the actions that will result in delivery of the materials or services set forth in the LOA that was accepted by a foreign country or international organization.
SAMM Glossary, as of 12 September 2026
Glossary entry →Open the manual’s entry → (opens in new tab)
Arms Export Control Act (AECA)
The basic U.S. law providing the authority and general rules for the conduct of Foreign Military Sales and commercial sales of defense articles, defense services, and training. The Arms Export Control Act (AECA) came into existence with the passage of the Foreign Military Sales Act (FMSA) of 1968. An amendment in the International Security Assistance and AECA of 1976 changed the name of FMSA to the AECA.
SAMM Glossary, as of 12 September 2026
Glossary entry →Open the manual’s entry → (opens in new tab)
SAMM C9.11.1: Trust Fund Accounts.
“Defense Finance and Accounting Services - Indianapolis (DFAS-IN) performs accounting for FMS, account 11X8242, by executing against subsidiary accounts: 978242 (Deposits, Advances, Foreign Military Sales, Defense) - receipt of payments and 97-11X8242 (Advances, Foreign Military Sales, Executive, Defense) - disbursements to suppliers. The purchaser makes payments to DFAS-IN for deposit into the FMS Trust Fund (unless the purchaser has an …”
Security Assistance Management Manual, as of 11 September 2026
DoD Financial Management Regulation 7000.14-R, Volume 15 (Security Cooperation Policy)
DoD FMR Vol 15 · Regulation
SAMM C9.3.10: Foreign Military Sales Trust Fund.
“The FMS Trust Fund is used for payments received from purchasers and disbursements made against implemented FMS cases. This fund is cited directly on contracts for the procurement of defense articles and/or services for the purchaser, or it is used to reimburse DoW Component appropriations for deliveries from DoW stocks or services performed by DoW employees. DSCA manages the FMS …”
Security Assistance Management Manual, as of 5 October 2026
SAMM C9.11.2: Federal Reserve Bank New York Accounts.
“Some countries may establish an account with the FRB New York, for their FMS deposits. An agreement between the FMS purchaser's defense organization, the purchaser's central bank (or an acceptable equivalent), FRB New York and DSCA identifies the terms, conditions, and mechanics of the account's operation. FMS purchasers should contact the FRB New York or the DSCA (Office of Business …”
Security Assistance Management Manual, as of 11 September 2026
SAMM C9.11.4: Payment Identification.
“Each deposit made into the FMS Trust Fund is recorded to the appropriate FMS case. If the payment cannot be identified to a specific case, it is deposited in the FMS purchaser’s Holding Account pending identification.”
Security Assistance Management Manual, as of 11 September 2026
SAMM C9.11.5: Excess Funds.
“Payments received for an FMS case may exceed the final case value or the highest financial requirement (all financial commitments billed to date, plus all financial commitments not yet billed (e.g., contracts awarded but not delivered), and must include below-the-line surcharges). Upon closure, excess funds are retained in the purchaser’s Holding Account pending further instructions. Excess case collections can be …”
Security Assistance Management Manual, as of 11 September 2026
SAMM C16.3.10.2
“For FMS cases funded with national funds, the USG is generally prohibited from unilaterally transferring funds from a holding account or another case to liquidate the payment shortfall. In this situation, DFAS-IN notifies the purchaser quarterly of the amount owed to close the case. The purchasers may choose to either wire transfer to DFAS-IN the amount due, authorize DFAS-IN to …”
Security Assistance Management Manual, as of 11 September 2026
SAMM C9.11.6: Movement of Purchaser Funds.
“DFAS-IN moves national funds to and from Holding Accounts or between cases only when such requests are channeled through the FMS purchaser’s designated representative. The use of notes or other references in LOA documents (Basic, Amendment, or Modification) concerning transfers or refunds of FMS purchaser funds, is not authorized. IAs do not enter any remarks on LOA documents transferring purchaser …”
Security Assistance Management Manual, as of 11 September 2026
SAMM AP7.C4.12.5
“Disposition of funds originating from cash-funded cases requires DFAS-INto transfer funds originating from cash-funded to the FMSTrust Fund holding account 7QQ. This holding account serves as a temporary repository of those funds and provides an appropriate audit trail for monitoring CCSA refunds. DSCA (OBO/FPRE) requests that purchasers respond within a reasonable time frame with their authorizations to transfer these funds …”
Security Assistance Management Manual, as of 9 November 2026
SAMM C9.11: Foreign Military Sales Payments from Purchasers.
“The Arms Export Control Act (AECA) (22 U.S.C. 2751) normally requires Foreign Military Sales (FMS) monies to be collected in advance of delivery, service performance, or contractual progress payments. Accumulation of large balances in purchaser Trust Fund accounts for substantial periods should be avoided, except for contract holdbacks and other accrued or potential liabilities, or when the purchaser requests an …”
Security Assistance Management Manual, as of 5 October 2026
SAMM AP7.C2.8.1
“Expenditure Authority (EA) is required before any disbursements (including reconciliation adjustments) are made against any case (Refer to Figure AP7.C2.F9.). For vendor payments, EA is requested as the payment voucher is processed, usually the day before the disbursement is made. An EA request checks "available cash" at country level (not case level) within the Foreign Military Sales (FMS) Trust Fund …”
Security Assistance Management Manual, as of 30 September 2026